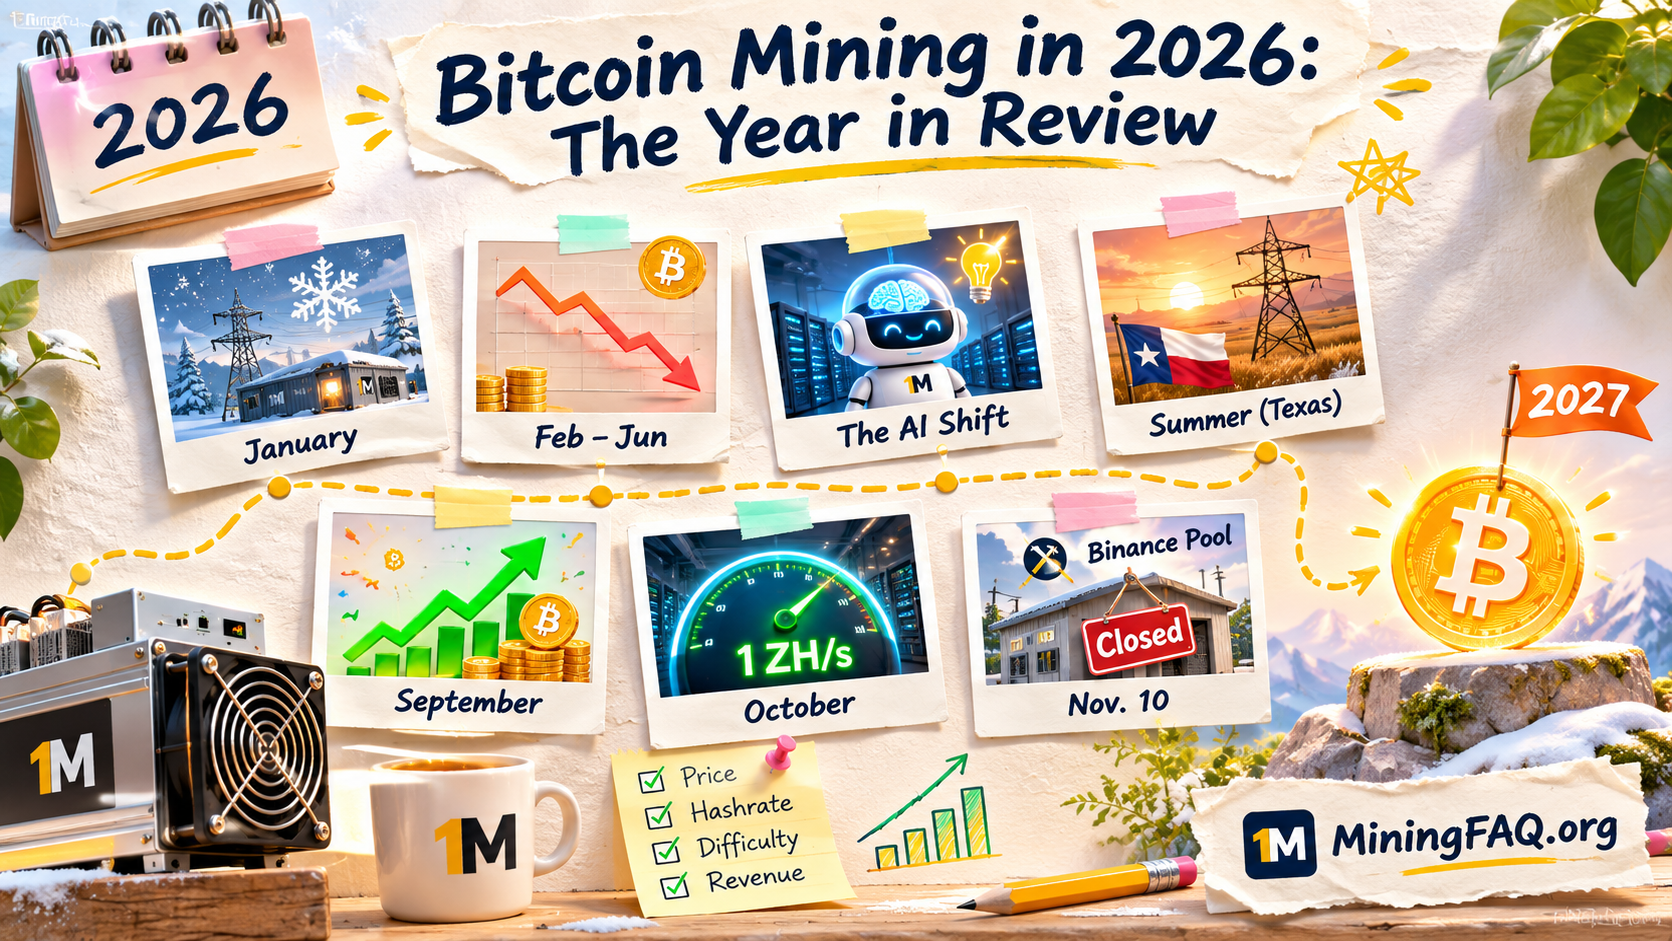
If you mined Bitcoin in 2026, you probably felt every part of the cycle. The year brought a severe winter curtailment, Bitcoin’s slide to roughly $59,000, record-low hashprice, declining difficulty, an accelerating shift by public miners toward AI and high-performance computing—and then a sharp recovery in network hashrate during the autumn.
By October, Bitcoin’s seven-day network hashrate was back above 1 zettahash per second, difficulty was climbing again and Binance had announced that it would discontinue Binance Pool on November 10.
It wasn’t a boring year, and it wasn’t an easy one. But it produced some unusually clear lessons about electricity cost, hardware efficiency and how quickly mining economics can change.
In this review, I’ll walk through the biggest events of 2026 so far, look at the numbers that defined the year and explain what they could mean for miners heading into 2027.
Figures are updated through early November 2026. November and December are not complete, so this is a year-to-date review rather than a final full-year report.
2026 at a Glance
| Metric | Figure |
|---|---|
| Bitcoin price peak used in this review (Oct. 6, 2025) | ~$124,485 |
| Bitcoin 2026 cycle low (June 30) | ~$59,005 |
| Bitcoin price around Oct. 29 | ~$80,150 |
| Daily hashprice low (June 6) | $27.74/PH/s/day |
| Best monthly hashprice average so far | September: $39.33/PH/s/day |
| Major 7-day hashrate weather low | ~833 EH/s in late January |
| Summer 7-day hashrate low | ~853 EH/s around June 9 |
| 7-day hashrate high in October | ~1,088 EH/s on Oct. 26 |
| 2026 difficulty low | 124.93T after the June 14 adjustment |
| Difficulty after Oct. 29 adjustment | 148.36T |
| All-time difficulty record | 155.97T on Oct. 29, 2025 |
| January miner revenue | ~$1.15B |
| September miner revenue | ~$1.12B, the best month since January at the time |
| September fees as share of block rewards | ~0.63% |
The Year, Month by Month
January: A Strong Start, Then a Freeze
Miners started 2026 in decent shape. January brought about $1.15 billion in total mining revenue, a figure no other month this year has topped.
Then the weather hit. According to Hashrate Index’s analysis of the return to 1 ZH/s, a late-January Arctic blast took roughly 200 EH/s offline, dragging the seven-day average hashrate from about 1,051 EH/s down to 833 EH/s. Much of that was North American miners powering down so the grid could keep homes warm. It was a vivid reminder that Bitcoin mining is now deeply tied to the electricity grid, for better and for worse.
February to June: The Long Slide
Bitcoin’s price, already well below its October 2025 peak of $124,485, kept falling through the first half of the year. Hashprice fell with it, hitting a low of about $27.74 per PH/s per day on June 6. Bitcoin itself bottomed near $59,005 on June 30, a drawdown of roughly 53% from the peak.
This was the period that separated efficient miners from everyone else. Older machines on expensive power simply couldn’t cover their electricity bills. OneMiners estimates that the 2025–26 sell-off pushed out about 27% of the network’s hashrate at its worst, starting with the least efficient hardware.
March also gave us one of the year’s stranger technical moments: a rare two-block reorg on March 23, when Foundry’s chain beat out competing blocks from AntPool and ViaBTC. It resolved exactly as Bitcoin’s rules intend, but it got people talking about pool concentration.
The AI Shift: Public Miners Redirect Power
One of the biggest structural stories of 2026 was the movement of publicly traded Bitcoin miners toward AI and high-performance computing infrastructure.
OneMiners’ 56 EH/s Unplugged: The 2026 Hashrate Contraction Explained summarizes industry research estimating that listed miners removed roughly 56 EH/s of Bitcoin mining capacity during the first half of 2026, equivalent to about a 15% contraction among the companies examined.
The same analysis says AI and HPC revenue at those companies increased about 52% from Q1 to Q2, and that AI-related revenue overtook mining revenue at some leading operators.
Those figures should be treated as a OneMiners/industry-analysis snapshot rather than a measurement of the entire Bitcoin mining sector, but the broader direction is clear: some operators increasingly see their electrical infrastructure as valuable for workloads other than Bitcoin.
One reason is capital economics. OneMiners cites industry estimates of roughly $8–15 million per MW to build AI data-center capacity compared with roughly $0.7–1 million per MW for Bitcoin mining infrastructure. AI requires dramatically more upfront capital, but long-term compute contracts can offer more predictable revenue than Bitcoin mining.
The shift is not finished. OneMiners’ October follow-up notes that at least another 35 EH/s of public-miner capacity was scheduled to leave Bitcoin mining, including planned transitions at IREN and Cipher.
That does not necessarily mean the same mining machines are simply moved somewhere else. Hashrate can recover through a mixture of relocated hardware, newer ASIC deployments and previously curtailed machines returning online.
Summer: Curtailment and the Bottom
Summer kept pressure on the network, especially during ERCOT’s Four Coincident Peak season. Hashrate Index identifies a summer seven-day hashrate low around 853 EH/s in June, while the network repeatedly dipped below 900 EH/s through June, July and August as Texas miners curtailed during peak-demand periods. ERCOT’s four coincident peaks occurred on June 18, July 22, August 24 and September 12. Difficulty responded as designed, including a −10.09% adjustment on June 14 and another −5.00% on July 11.
For anyone who had cheap, stable power through the summer, this was quietly one of the best times of the year. Difficulty was falling, so each machine earned more bitcoin per day. OneMiners called it a “low-difficulty window,” and it was real while it lasted.
September: The Recovery
September brought one of the strongest mining-market improvements of the year.
According to Luxor’s September 2026 Hashrate Lookback, USD hashprice averaged $39.33 per PH/s/day, the highest monthly average since January. Bitcoin also strengthened, while network hashrate began recovering as ERCOT’s summer curtailment season ended.
Transaction fees remained extremely small, however, averaging only about 0.63% of total block rewards—the fifteenth consecutive month below 1%.
September also brought two important policy events. On September 15, the U.S. Senate failed to invoke cloture on the motion to proceed to the Digital Asset Market Clarity Act, with the vote failing 49–50. The following day, the Federal Reserve raised its target range by 25 basis points to 3.75–4.00%.
Neither event was a mining-specific policy change, but both were relevant to the broader capital and crypto-market environment.
October: Back Above 1 ZH/s
October delivered the strongest network rebound of the year.
The seven-day average Bitcoin hashrate crossed 1,000 EH/s on October 11 and reached approximately 1,088 EH/s on October 26. Difficulty then rose 5.92% on October 16 and another 5.54% on October 29, reaching 148.36T.
More competition came with a cost. Luxor’s October review shows USD hashprice falling from $40.15 at the start of October to $32.98 at month-end, despite the sharp increase in hashrate.
October also produced a major pool-industry announcement. On October 13, Binance announced that Binance Pool and its related mining services will be discontinued on November 10, 2026. Until that cutoff, Binance says the pool continues operating normally.
So it is more accurate to say Binance announced its exit from mining-pool services, rather than saying it had already shut down during October.
The Trends That Defined 2026
1. Efficiency Became Everything
The machines that kept earning this year were the efficient ones. OneMiners’ analysis of whether Bitcoin mining is still worth it in 2026 puts it simply: mining pays “above one specific electricity price, and no below it.” Using September’s hashprice, OneMiners calculated these break-even electricity rates:
| Efficiency | Example machine | Break-even power rate (Sept 2026) |
|---|---|---|
| ~9.5 J/TH | Antminer S23 Hyd | ~$0.178/kWh |
| ~12 J/TH | Antminer S21 XP Hyd | ~$0.141/kWh |
| ~17.5 J/TH | Antminer S21 | ~$0.097/kWh |
Luxor’s data shows the same story from a different angle. In September, machines under 14 J/TH earned about $137 per MWh of electricity, while machines at 25–38 J/TH earned about $51, barely above the average industrial power cost of about $48.
Cassys looks at what this means for upgrade decisions in Best ASIC Miners to Consider Before 2027: Are Newer Machines Worth the Upgrade?, which is worth reading if you’re still running older hardware.
2. The Map Shifted
Bitcoin mining also moved around the world. According to Hashrate Index’s Global Hashrate Heatmap for Q4 2026:
| Country | Share of hashrate | Trend |
|---|---|---|
| United States | 35.6% (~335 EH/s) | Third straight quarterly decline |
| Russia | 18.1% (~170 EH/s) | Record share, biggest gain |
| China | 11.7% (~110 EH/s) | Down 24% year over year |
| Paraguay | 4.8% (~45 EH/s) | Steady |
| Oman | 3.0% (~28 EH/s) | Passed the UAE for fifth |
| UAE | 2.8% (~26 EH/s) | — |
| Ethiopia | 1.6% (~15 EH/s) | Down ~35% after a September power cut |
The US is still the clear leader, but its share is slipping as its public miners move power to AI. Meanwhile, Russia, Oman, Pakistan and Venezuela are growing. Ethiopia’s drop is a good reminder that cheap hydropower comes with its own risk: low reservoir levels can mean sudden power cuts.
3. Transaction Fees Stayed Tiny
This is the trend that worries me most, and it gets far less attention than it deserves. In September, transaction fees made up just 0.63% of block rewards, the fifteenth straight month below 1%. In other words, miners are living almost entirely on the block subsidy.
That’s manageable today, but the 2028 halving will reduce Bitcoin’s block subsidy from 3.125 BTC to 1.5625 BTC. If Bitcoin price, difficulty and transaction-fee revenue were all unchanged, the subsidy portion of mining revenue—and therefore electricity-only break-even rates—would fall by roughly half. Real conditions will almost certainly change before then, which is why miners should treat “half the current revenue” as a stress-test scenario rather than a forecast.
4. Pool Concentration and Stratum V2
In a recent week, the three largest pools (Foundry USA, AntPool and F2Pool) found about 64% of blocks. We saw a handful of one-block reorgs between big pools in August and September, and the Binance Pool closure pushed a little more hashrate toward the big names.
The hopeful side is Stratum V2. In May 2026, seven major mining organizations—including ANTPOOL, F2Pool, Foundry, SpiderPool, DMND, MARA Foundation and Block Inc.—joined the Stratum V2 Working Group. The participating pool operators represented roughly three-quarters of global hashrate at the time. In June, DMND and GoMining then mined mainnet block 955,318 using a miner-declared template. Production Job Declaration adoption remains small, but it has moved from theory into real pooled mining.
5. Small Miners Still Had Their Moments
Not every story was about big companies. In July, a Bitaxe-class home miner solo-mined block 957,382 and collected more than 3 BTC. It’s a lottery, not a strategy, but it was a fun reminder that Bitcoin remains open to anyone with a machine and an internet connection.
My Take: What 2026 Taught Us
Electricity became an even bigger competitive advantage. Hardware efficiency, uptime, Bitcoin price and difficulty still matter, but 2026 repeatedly showed how strongly electricity cost shapes mining outcomes. Winter curtailment, summer 4CP events and the AI/HPC shift all revolved around access to power and what that power was worth.
AI is now a real competitor for mining infrastructure. Public miners redirected meaningful electrical capacity toward AI and HPC during 2026. That reduced some listed-company mining capacity, but it did not permanently reduce Bitcoin’s network hashrate. By October, the seven-day network average was above 1 ZH/s again. That recovery may reflect a mixture of returning curtailed machines, new ASIC deployments and capacity moving between operators.
Older hardware became much more location-dependent. S19-generation machines did not suddenly become useless everywhere. But when hashprice fell into the high-20sandlow-30s, older hardware required exceptionally cheap electricity to remain attractive. The same ASIC can be uneconomic at a retail rate and still operate at a low-cost industrial site.
2028 deserves serious scenario planning. The next halving will cut the block subsidy from 3.125 BTC to 1.5625 BTC. It will not automatically cut every miner’s dollar revenue exactly in half because Bitcoin price, difficulty and fees will also change. But with transaction fees currently contributing less than 1% of block rewards, miners should stress-test new hardware against substantially lower subsidy revenue.
What to Watch in 2027
- Hashrate and difficulty: Luxor’s late-October forward market moved away from the earlier expectation that the network would only cross 1 ZH/s in 2027—the network already did it in October. The newer curve instead points to roughly 1.05 ZH/s around year-end, with more modest growth priced beyond that.
- AI/HPC conversions: Watch which public miners continue redirecting electrical capacity and whether their Bitcoin ASIC fleets are retired, relocated or sold.
- Transaction fees: September fees represented only about 0.63% of block rewards. A sustained increase would make miners less dependent on the subsidy ahead of 2028.
- Stratum V2: Focus on pools actually deploying Job Declaration with miner-selected templates, not simply joining the Stratum V2 Working Group.
- New hardware: Sub-10 J/TH machines are emerging at the flagship end of the ASIC market, but they are not yet the standard across the installed network.
How to Prepare as a Miner
- Know your electricity-only break-even rate. A useful approximation is hashprice divided by 24 × efficiency in J/TH. Then subtract room for pool fees, hosting costs, downtime and hardware depreciation.
- Compare your electricity contract with current hosting alternatives. OneMiners’ current hosting network lists 17 live data centers across five continents, 1,964 MW of capacity, 98%+ average uptime and seven-year prepaid electricity starting around 3.6¢/kWh in Nigeria. Published site pricing includes management services.
- Do not assume older hardware must be discarded. Relocating an inefficient machine from expensive electricity to a lower-cost site can sometimes change the economics more than replacing it immediately.
- Keep control of your pool choice. The announced Binance Pool shutdown is a good reminder to configure backup pools and avoid depending on a single endpoint.
- Model the 2028 halving before buying equipment. Run scenarios with lower subsidy revenue, higher difficulty and several electricity prices rather than relying on today’s profitability alone.
For miners considering an upgrade, Cassy Soriano’s Medium article Best ASIC Miners to Consider Before 2027: Are Newer Machines Worth the Upgrade? is still worth keeping here because it focuses specifically on the trade-off between efficiency gains, hardware cost and electricity rates.
OneMiners also fits naturally into that decision. Its advantage is not that it can make weak hardware profitable under every market condition; it is that miners can compare hardware with published hosting rates, fixed long-term electricity options and professionally managed infrastructure rather than relying only on expensive residential power.
Frequently Asked Questions
Was 2026 a good year for Bitcoin mining? It was mixed. January and September were strong, while the first half of the year was tough, with record-low hashprice in June.
What was the biggest change in Bitcoin mining in 2026? The shift of public miners toward AI and high-performance computing, which removed about 56 EH/s in the first half alone.
Did Bitcoin’s hashrate grow in 2026? It fell sharply in the first half, then recovered strongly, returning above 1 ZH/s in October.
Which country mines the most Bitcoin? The United States, with about 35.6% of hashrate, followed by Russia (18.1%) and China (11.7%).
Is Bitcoin mining still profitable heading into 2027? Yes, for efficient machines on cheap power. Older machines on retail electricity generally aren’t.
What’s the biggest risk for miners in the next two years? The 2028 halving, combined with very low transaction fees.
The Bottom Line
2026 was the year Bitcoin mining grew up a little more. Price swings still mattered, but the bigger forces were electricity, efficiency and competition from AI. The network proved it could lose huge amounts of hashrate to storms, curtailment and corporate pivots, and still come back stronger, above 1 ZH/s by October.
For miners, the lesson is the same one Bitcoin mining has always taught, just louder: efficient hardware, cheap and stable power and a long-term plan are what keep you in the game.
Planning your 2027 setup? Use the MiningFAQ Profitability Calculator to test your hardware against today’s difficulty and your electricity rate.
This article is for educational purposes only and is not financial advice. Figures are as of early November 2026 and may change. Always check live data before making mining decisions.